A workplace injury can make even a straightforward medical appointment feel loaded with risk: Will I be billed? Does my claim need to be approved first? Are valid claims fee free? For injured workers, the answer is often that approved WorkCover treatment can be provided with no out-of-pocket cost. But the details matter, especially while a claim is still being assessed or if liability is disputed.
At Workcover.Hills Doctor, the priority is fast, friendly, and professional care alongside clear documentation for your claim. Understanding how fees usually work can help you seek treatment promptly, keep your paperwork moving, and focus more of your energy on recovery.
What “fee free” usually means for a valid claim
In the New South Wales workers’ compensation system, medical and related treatment that is reasonably necessary because of a work injury may be paid through the workers’ compensation insurer. When a claim is accepted and the treatment is approved or covered under the relevant arrangements, the worker generally should not have to pay an out-of-pocket fee for that covered service.
“Fee free” does not mean every health service, at any provider, at any time is automatically covered. It means the cost of eligible treatment is generally directed to the insurer rather than to you. The provider needs the correct claim information, and the service must relate to your workplace injury and fall within the applicable approval and fee arrangements.
This distinction is useful because injured workers often delay care while waiting for an insurer decision. Early assessment is still important. A doctor can assess the injury, provide a certificate of capacity where appropriate, document symptoms and restrictions, and coordinate treatment that supports a safe recovery and return to work.
When your medical appointment may have no out-of-pocket cost
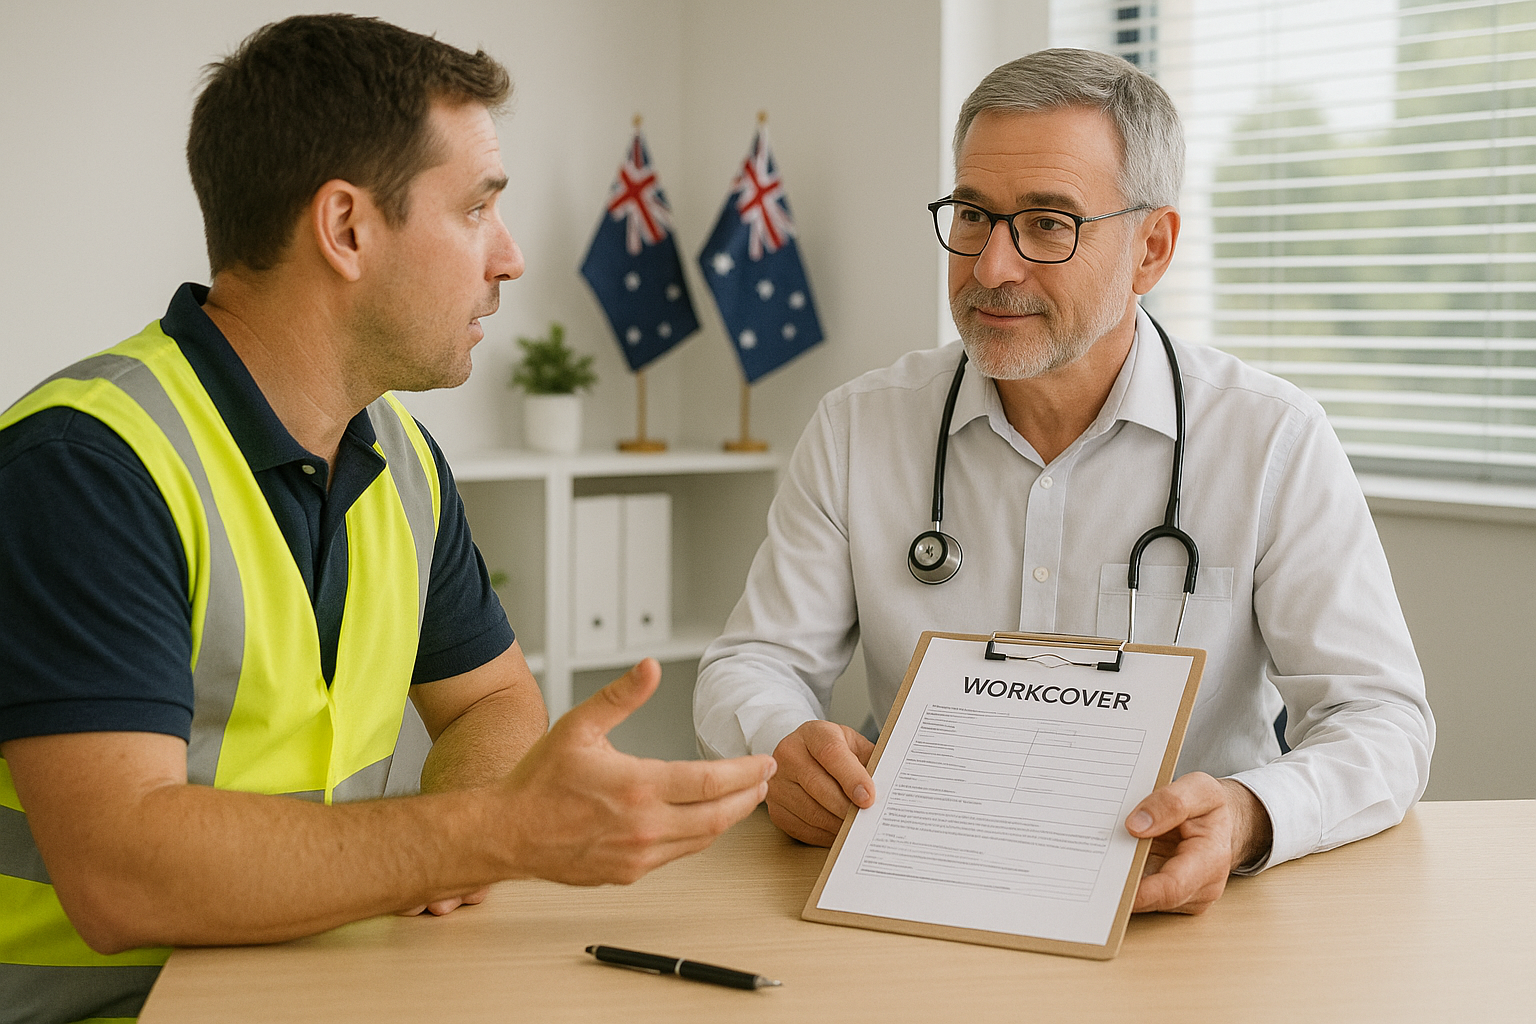
For an accepted WorkCover claim, your consultation, medical certificate, injury assessment, and treatment planning may be billed directly to the insurer when the required claim details are available. The same can apply to referrals and care from allied health providers, depending on the treatment, provider requirements, and insurer authorization.
The practical question is not only whether you have lodged a claim. It is whether there is enough information for your provider to confirm the billing pathway. Bring your claim number if you have one, the insurer’s name, your employer’s details, and any correspondence confirming that your claim has been accepted. If you have been given a case manager’s contact details, bring those as well.
A valid claim is generally one connected to a work-related injury or illness, supported by medical evidence and managed through the workers’ compensation process. The insurer makes decisions about liability and payment. Your treating doctor’s role is different but equally important: accurately assessing your condition, recording the clinical facts, explaining functional restrictions, and providing legally compliant medical documentation.
If your claim is still pending
A pending claim is not the same as a rejected claim. The insurer may still be gathering information from you, your employer, and your treating providers before making a decision. During this period, fee arrangements can vary based on the circumstances of your case and the treatment required.
Do not assume that you must simply wait without support. Tell the clinic that your claim is pending when you book. Provide every available detail, including the date of injury, employer information, claim number, and insurer contact. The practice can explain the available appointment and billing process before you attend, so there are no surprises.
If the insurer has denied the claim
A denied claim can be stressful, particularly when you are still in pain and need current medical evidence. A denial does not necessarily mean your injury is not real or that you should stop getting appropriate care. It means the insurer has disputed liability or coverage, and you may need to understand the reasons for that decision and your options.
Workcover.Hills Doctor describes waived fees in denied-claim situations. That policy is designed to reduce a financial barrier when a patient needs assessment and documentation during a difficult point in the claims process. Confirm the current arrangement with the practice when booking, because the scope of any waived fee and the services included should always be clear in advance.
What can affect whether a claim is fee free?
Medical billing in a compensation claim is not only about the diagnosis. It can depend on claim status, the service being requested, insurer requirements, and whether the treatment is considered reasonably necessary for the work injury.
For example, a routine consultation to assess a recent work injury may follow a different billing process from a specialized report requested for legal proceedings. Similarly, an insurer may require a treatment plan or prior approval for some services, particularly if treatment is ongoing, more complex, or outside standard pathways.
There can also be questions where a person had a pre-existing condition. A prior back problem does not automatically prevent a claim after a new workplace incident. What matters is careful clinical assessment: what symptoms existed before, what changed after the incident, what work duties were involved, and what treatment is now medically appropriate. Clear, contemporaneous medical records can be very important in these situations.
For motor vehicle accident and public liability matters, the cost arrangements are not identical to WorkCover. CTP insurers, liability insurers, and legal representatives may each have different documentation and authorization requirements. Always let the practice know which type of claim you have so the appointment, reporting, and billing process can be organized correctly.
How to prepare for a WorkCover appointment
Good preparation helps your doctor provide an accurate assessment and helps prevent avoidable delays in claim documentation. You do not need to understand every insurance rule before attending. You do need to provide a clear account of what happened and how the injury is affecting your capacity to work and manage daily activities.
Bring identification, your employer’s details, your claim number and insurer information if available, and any previous medical records or imaging relevant to the injury. It is also helpful to bring a list of medications and a brief timeline of your symptoms. If your employer has offered suitable duties, bring that information so your doctor can consider whether the duties match your current capacity.
Be specific during the consultation. Explain how the injury occurred, where you feel pain or limitation, what movements make symptoms worse, and what tasks you cannot safely perform. If you are struggling with sleep, driving, concentration, anxiety, or household activities, say so. These details help create a fuller clinical picture, not just a diagnosis on paper.
Why accurate documentation protects your recovery and claim
A medical certificate is more than an administrative form. It communicates your current capacity, restrictions, treatment needs, and review date to the people managing your claim. When it is accurate, it can support safe duties rather than pressure to return to tasks that may worsen an injury.
Detailed clinical notes and reports also help align the wider care team. Employers, insurers, rehabilitation providers, allied health professionals, and legal representatives may all need information at different stages. A reliable medical partner can coordinate referrals for physiotherapy, chiropractic care, occupational therapy, psychology, speech therapy, or dietitian support where clinically appropriate.
That coordination does not guarantee an insurer decision. It does, however, ensure that decisions are informed by clear medical evidence rather than incomplete paperwork or an outdated understanding of your condition.
Questions to ask before you book
It is reasonable to ask directly whether your appointment can be billed to WorkCover and whether you will have any out-of-pocket expense. Ask what claim details the clinic needs, whether an accepted claim or insurer approval is required for the specific service, and what happens if the insurer later disputes payment.
You can also ask how quickly certificates and reports are completed, whether the doctor can coordinate referrals, and what information your employer will receive. The answers should be clear and practical. You should never feel embarrassed about asking for an explanation of fees or claim paperwork.
If you have been injured at work, timely care and accurate records are often the best next steps. Bring the information you have, be open about your symptoms and work demands, and let your treating team help make the process clearer every step of the way.