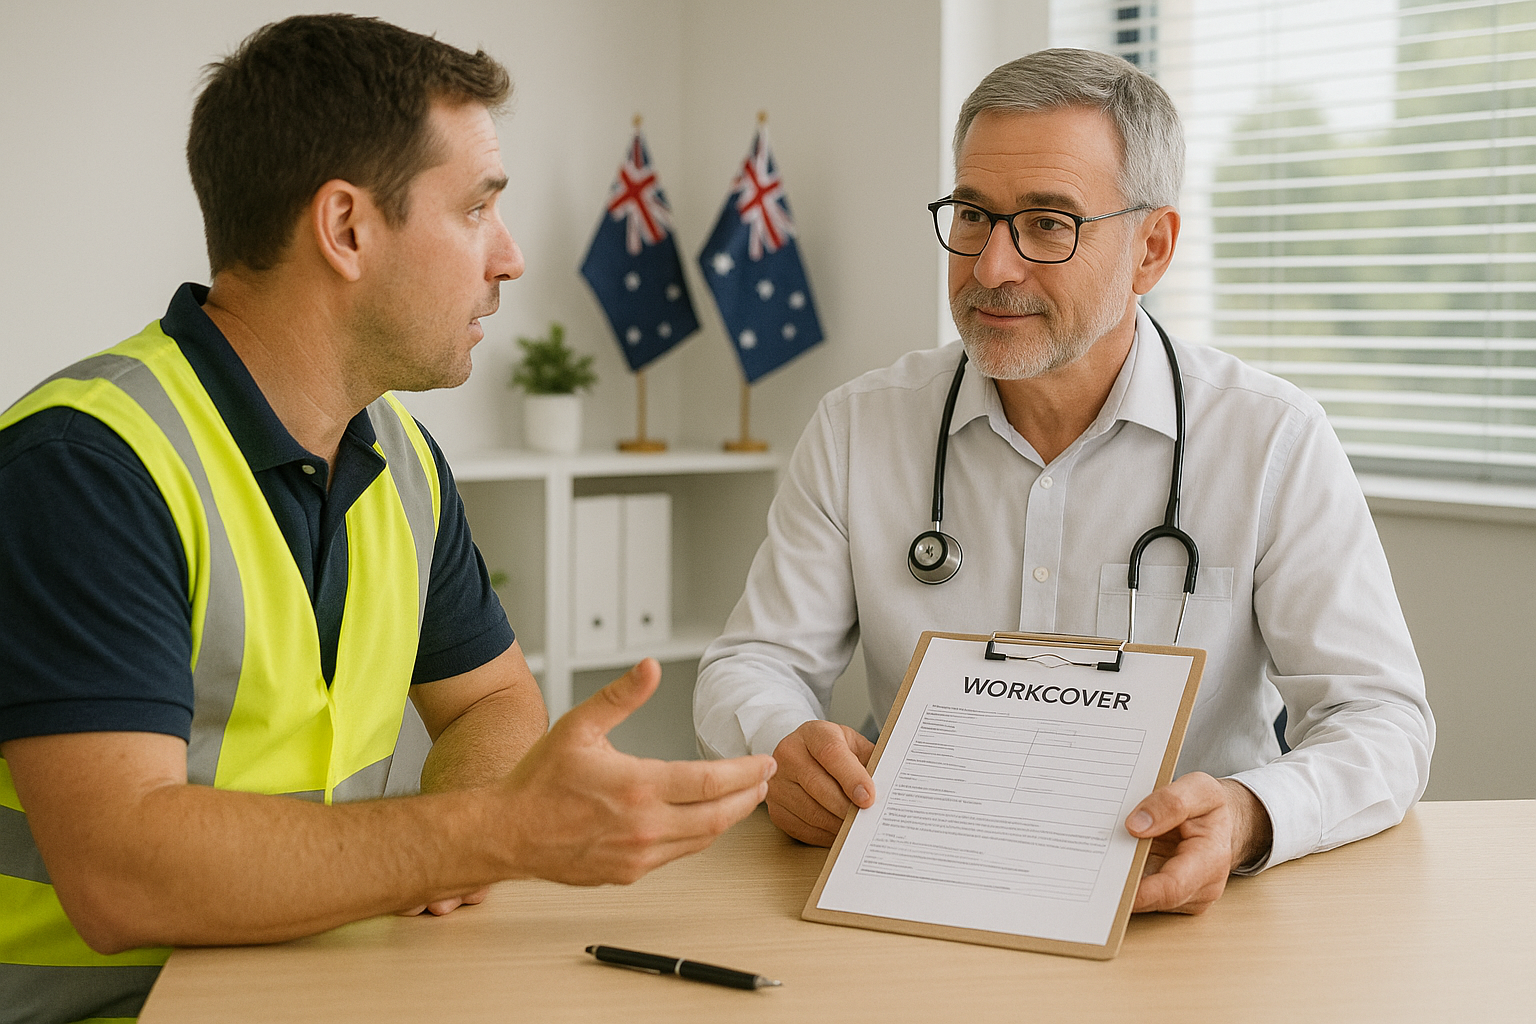
A workplace injury can create two urgent questions at once: “What treatment do I need?” and “Who is going to pay for it?” Understanding WorkCover medical expenses NSW can take some pressure off while you focus on diagnosis, treatment, and a safe return to work. The key is getting appropriate care early, reporting the injury promptly, and making sure your medical evidence and claim details are accurate from the start.
For many injured workers, approved workers’ compensation claims can cover the reasonable costs of medical treatment related to a workplace injury or illness. Coverage is not automatic for every service or every expense. It depends on the injury, the treatment recommendation, the status of your claim, and whether the insurer accepts that the care is reasonably necessary.
What medical expenses may be covered in NSW?
When a workers’ compensation claim is accepted, the insurer may fund treatment that is reasonably necessary because of your work-related injury. This can include an initial medical assessment and ongoing care needed to support recovery, manage symptoms, improve function, or prepare for a return to suitable duties.
Common examples include treatment from a general practitioner, specialist consultations, physiotherapy, chiropractic care, occupational therapy, psychology, and other approved allied health services. Depending on your circumstances, coverage may also extend to diagnostic imaging, pathology, prescribed medication, surgery, hospital treatment, rehabilitation programs, and medical aids or equipment.
The practical question is not simply whether a service might help. The insurer will usually consider whether it is connected to the work injury, clinically appropriate, and supported by medical evidence. A detailed assessment, clear treatment plan, and accurate certificate of capacity can make that connection easier to understand.
Some injuries require short-term treatment only. Others, such as spinal injuries, complex fractures, chronic pain conditions, or psychological injuries, may need coordinated care across several providers. In these cases, regular medical review and consistent documentation are especially important. They show how the injury is affecting your work capacity, what treatment has been tried, and why further care is recommended.
WorkCover medical expenses NSW and claim approval
You do not necessarily need to wait until every claim issue is resolved before seeking medical attention. Your health should come first. However, payment arrangements can differ depending on whether the insurer has accepted liability, whether your employer has notified the injury, and whether the service has been approved.
After you report the injury to your employer and lodge a workers’ compensation claim, the insurer assesses the available information. This commonly includes your certificate of capacity, medical records, claim form, employer information, and any details about how the injury occurred. If the insurer accepts the claim, it can approve reasonable medical and related expenses within the scope of the claim.
Where liability is still being investigated, it is sensible to ask the treating practice how billing will be managed. Do not assume that every provider will bill the insurer directly or that every recommended treatment has already been approved. A claims-literate medical practice can help identify what documentation is needed, provide clinically accurate reports, and communicate with the relevant parties where appropriate.
At Workcover.Hills Doctor, valid WorkCover claims can generally be managed without out-of-pocket medical consultation costs, helping injured patients access fast, friendly, and professional care without adding unnecessary financial stress. The practice can also explain its approach if a claim has been denied or is still under review.
The medical documents that support your treatment
Medical paperwork can feel like an extra burden when you are already in pain. Yet it is often the bridge between your injury, your treatment, and the benefits you need. The goal is not to create paperwork for its own sake. It is to provide a clear, factual record that supports safe care and fair claim management.
Your treating doctor may prepare a certificate of capacity outlining your diagnosis, current symptoms, functional restrictions, treatment needs, and capacity for work. This document can help your employer consider suitable duties and help the insurer understand why time away from certain tasks, modified hours, or workplace restrictions may be required.
For more complex claims, a medical report may address your injury history, examination findings, treatment progress, prognosis, and recommended referrals. Accurate reports matter because insurers, employers, lawyers, rehabilitation providers, and case managers may rely on them when making decisions. A report should be clinically independent, legally compliant, and specific enough to explain the connection between the work incident and your current treatment needs.
Bring any useful records to your appointment, including claim details, previous imaging, hospital discharge papers, medication lists, referral letters, and contact information for your insurer or case manager. If you do not have everything, do not delay necessary care. Your doctor can advise what is needed next.
When travel and other recovery costs may apply
Medical expenses are not always limited to the consultation room. Depending on the circumstances and approvals, a claim may also cover reasonable travel costs for treatment, as well as certain rehabilitation supports, equipment, or home assistance needs linked to the injury.
Travel reimbursement is usually more straightforward when you keep clear records. Save receipts, note appointment dates, and record the reason for travel. If your injury means you cannot drive safely, discuss this with your treating doctor and insurer before making regular transport arrangements.
The same principle applies to equipment and support services. A brace, ergonomic aid, mobility device, or home modification may be recommended in some cases, but approval often depends on the clinical reason and the insurer’s assessment. Ask before committing to expensive purchases unless you have been clearly advised otherwise.
Steps to protect your care and your claim
Early action can reduce avoidable delays. Report the injury to your employer as soon as possible, seek medical assessment, and give the doctor a clear account of what happened at work. Explain your symptoms, the physical or psychological demands of your role, and whether you have had any similar injuries before.
From there, keep your treatment plan consistent. Attend recommended appointments, follow medical advice where practical, and raise concerns early if treatment is not helping or your symptoms worsen. Missing appointments or changing providers repeatedly without explanation can make it harder for everyone to understand your recovery pathway.
Communication also matters. Keep copies of certificates, receipts, insurer letters, and treatment approvals. Let your doctor know if your insurer requests information, if your employer offers modified duties, or if your work restrictions are not being followed. A medical certificate should reflect your actual capacity, not pressure from the workplace or anxiety about the claim.
If you have a lawyer, case manager, or rehabilitation provider, coordinated communication can prevent duplicated assessments and conflicting recommendations. With your consent, your treating team can provide relevant updates that keep the claim moving while protecting your clinical needs.
Questions injured workers often ask
Do I need a referral to see a WorkCover doctor?
A referral is not always required for an initial assessment. However, some specialist and allied health services may require a referral or insurer approval. Booking early with a doctor experienced in workplace injuries can help you understand the right pathway.
Can I choose my own doctor?
In many situations, you can choose your treating doctor. Choose someone who listens carefully, understands workplace injury management, and can provide accurate certificates and reports. Your treating doctor should focus on your health and functional recovery, not simply the administrative process.
What if the insurer declines treatment?
Ask for the decision and reasons in writing. Your doctor may be able to provide further clinical information if the issue is missing evidence or an unclear treatment recommendation. If you disagree with a decision, consider obtaining advice about the review or dispute options available to you.
Will every expense be paid?
Not necessarily. Coverage depends on whether the expense is related to the accepted injury and considered reasonably necessary. Confirming approval before commencing costly or ongoing services can help prevent unexpected bills.
The right medical support should make a difficult process feel more manageable, not more confusing. Seek care promptly, keep your documentation clear, and work with providers who can support both your recovery and the practical steps behind your claim – every step of the way.